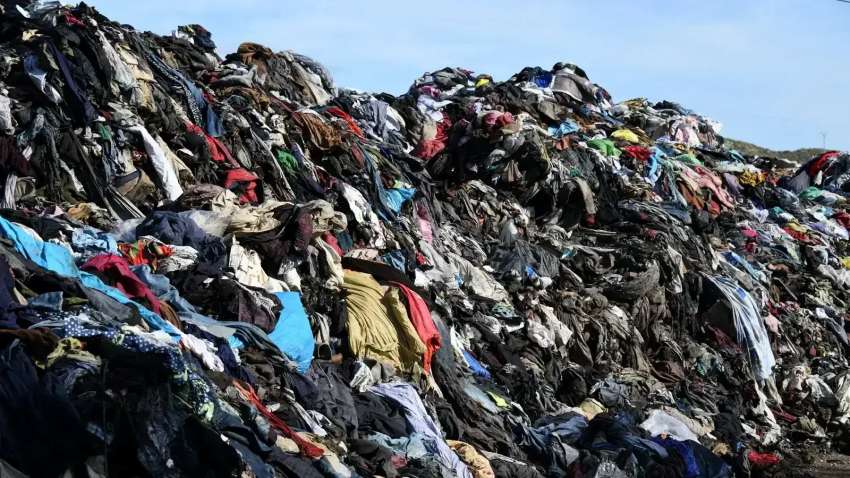
Global apparel emissions have crossed the one-billion-tonne mark as rapidly increasing synthetic-fibre production overwhelms gains made through factory-level clean energy investments. According to the Apparel Impact Institute’s (Aii) annual report, Taking Stock of Progress Against the Roadmap to Net Zero, sector greenhouse-gas emissions rose 7.5 per cent in 2023 to 944 million metric tonnes and climbed another 6.3 per cent in 2024 to approximately 1.004 billion tonnes. The nearly 14 per cent increase over two years puts the industry further away from its objective of halving emissions by 2030.
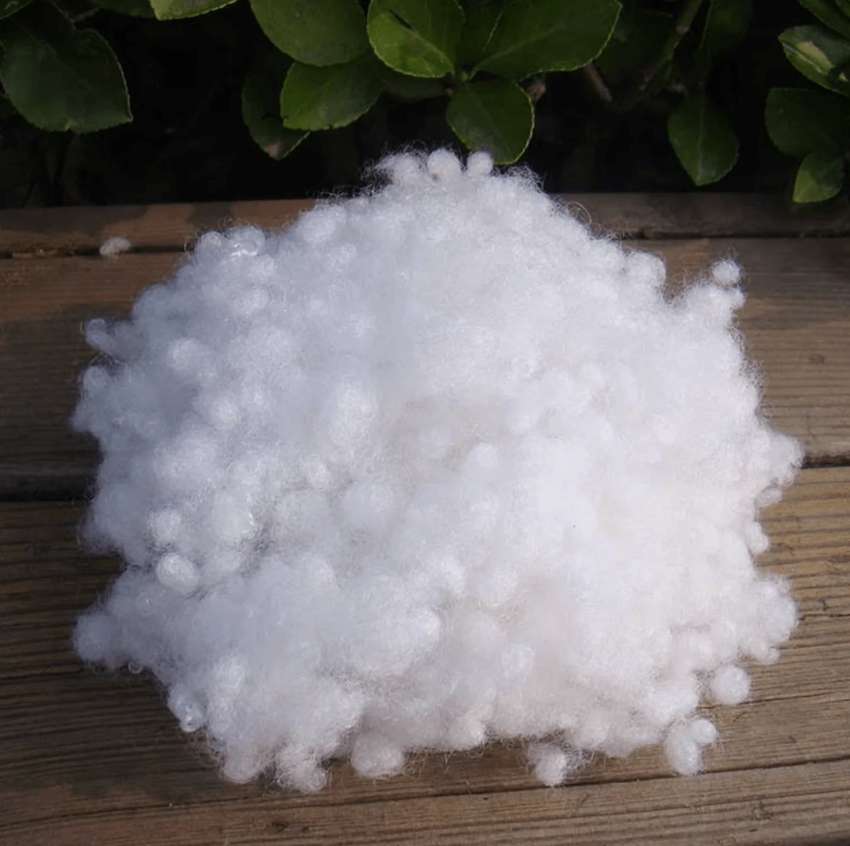
Polyester drives growth
The sharp increase in emissions coincides with record global fibre production. Textile Exchange data cited by Aii shows total fibre output rising from 125 million tonnes in 2023 to 132 million tonnes in 2024, compared with 116 million tonnes in 2022. Polyester accounted for 59 per cent of global fibre production in 2024, compared with 57 per cent a year earlier and 54 per cent in 2022.
|
Operations |
2022 Baseline |
2023 Performance |
2024 Performance |
2030 Target |
|
Total Apparel Sector GHG Emissions |
878 Mt |
944 Mt (+7.5%) |
1,004 Mt (1.0 Gt, +6.3%) |
489 Mt (1.5°C Alignment) |
|
Global Fiber Production Volume |
116 Mt |
125 Mt |
132 Mt |
Decoupled from Growth |
|
Polyester Share of Global Fiber |
54% |
57% |
59% |
Preferred / Circular Shift |
|
Brands with Approved Science-Based Targets |
100 (2021) |
450 |
700+ (as of mid-2026) |
Full Sector Adoption |
The numbers point to a problem: improvements in individual factories are being outweighed by growth in the volume of materials entering the global apparel system.
Virgin beats recycled
The economics of polyester remain central to the challenge. Virgin polyester continues to enjoy a cost and availability advantage over recycled polyester, particularly as large Asian petrochemical complexes deliver economies of scale. At the same time, supplies of recycled PET feedstock remain constrained. Textile recyclers compete with beverage and packaging companies for post-consumer bottles, while processing recycled material generally carries a higher cost. For apparel manufacturers operating with lower margins, the commercial incentive therefore remains focused towards virgin polyester.
This creates a difficult contradiction for the industry. Brands are under pressure to keep retail prices low, while suppliers are expected to invest in renewable energy, cleaner heat and lower-carbon materials. The result is that operational decarbonisation can coexist with rising overall emissions if material consumption continues to expand rapidly.
Asia faces grid constraints
The largest decarbonisation challenge remains upstream manufacturing. Tier II wet processing, dyeing and finishing, together with Tier III spinning and Tier IV fibre production, account for more than 70 per cent of fashion’s lifecycle emissions, according to the report. Manufacturing hubs across Asia face different versions of the same problem: carbon-intensive electricity, dependence on fossil-fuel boilers, high financing costs and limited access to renewable power.
China remains dominant in synthetic fibre extrusion and dyeing, where grid carbon intensity remains a challenge despite growing supplier-level renewable procurement. Bangladesh faces shortages in gas supply and limited access to clean industrial heat. Vietnam is working through delays in direct power-purchase mechanisms, while India’s fragmented textile base makes financing modernisation particularly difficult for smaller mills.
For SMEs, the capital required for electric boilers, renewable generation, wastewater recovery and other upgrades can be prohibitive without external financing or long-term purchasing commitments from brands.
Efficiency can deliver
Despite the sector-wide increase, large manufacturers are showing that significant emissions reductions are achievable. Shenzhou International Group Holdings, a major apparel manufacturer supplying brands including Nike, Adidas and Fast Retailing’s Uniqlo, shifted over 60 per cent of its electricity consumption to renewable sources in 2024. Ten of its production plants operated on 100 per cent renewable electricity, while combined Scope 1 and Scope 2 emissions were 16.8 per cent below 2020 levels.
Pakistan-based textile manufacturer Artistic Milliners has similarly committed more than $100 million towards solar, wind generation and thermal-water recovery across its manufacturing operations. Such investments show that factory-level decarbonisation can produce measurable results when supported by scale, capital and stable customer relationships.
Volume is the bigger problem
The wider industry, however, faces a bigger challenge. Ultra-fast-fashion models continue to increase the number of garments produced and encourage greater use of inexpensive virgin synthetics. The emissions associated with additional fibre production, processing, transportation and short product lifecycles can therefore exceed savings generated by cleaner factories.
For Aii, the challenge is one of capital allocation and structural transformation rather than isolated efficiency improvements. Its $250 million Fashion Climate Fund is designed to mobilise up to $2 billion in blended commercial capital for supply-chain decarbonisation, including coal replacement, clean heat and renewable power.
The industry's climate route will ultimately depend on whether such investment can move upstream and whether brands can reduce dependence on ever-growing volumes of low-cost virgin synthetic fibre. Without that shift, factory efficiency alone is unlikely to put global fashion back on its 2030 net-zero course.